Buying a second home in France follows a precise order of decisions: the use first, then the location, the journey and the full budget. This guide from Home Select, a prestige buyer’s agent (or buying agent) on the buyer’s side, takes each decision in turn, with the rules that apply in 2026 to mortgage finance, holiday letting and resale.
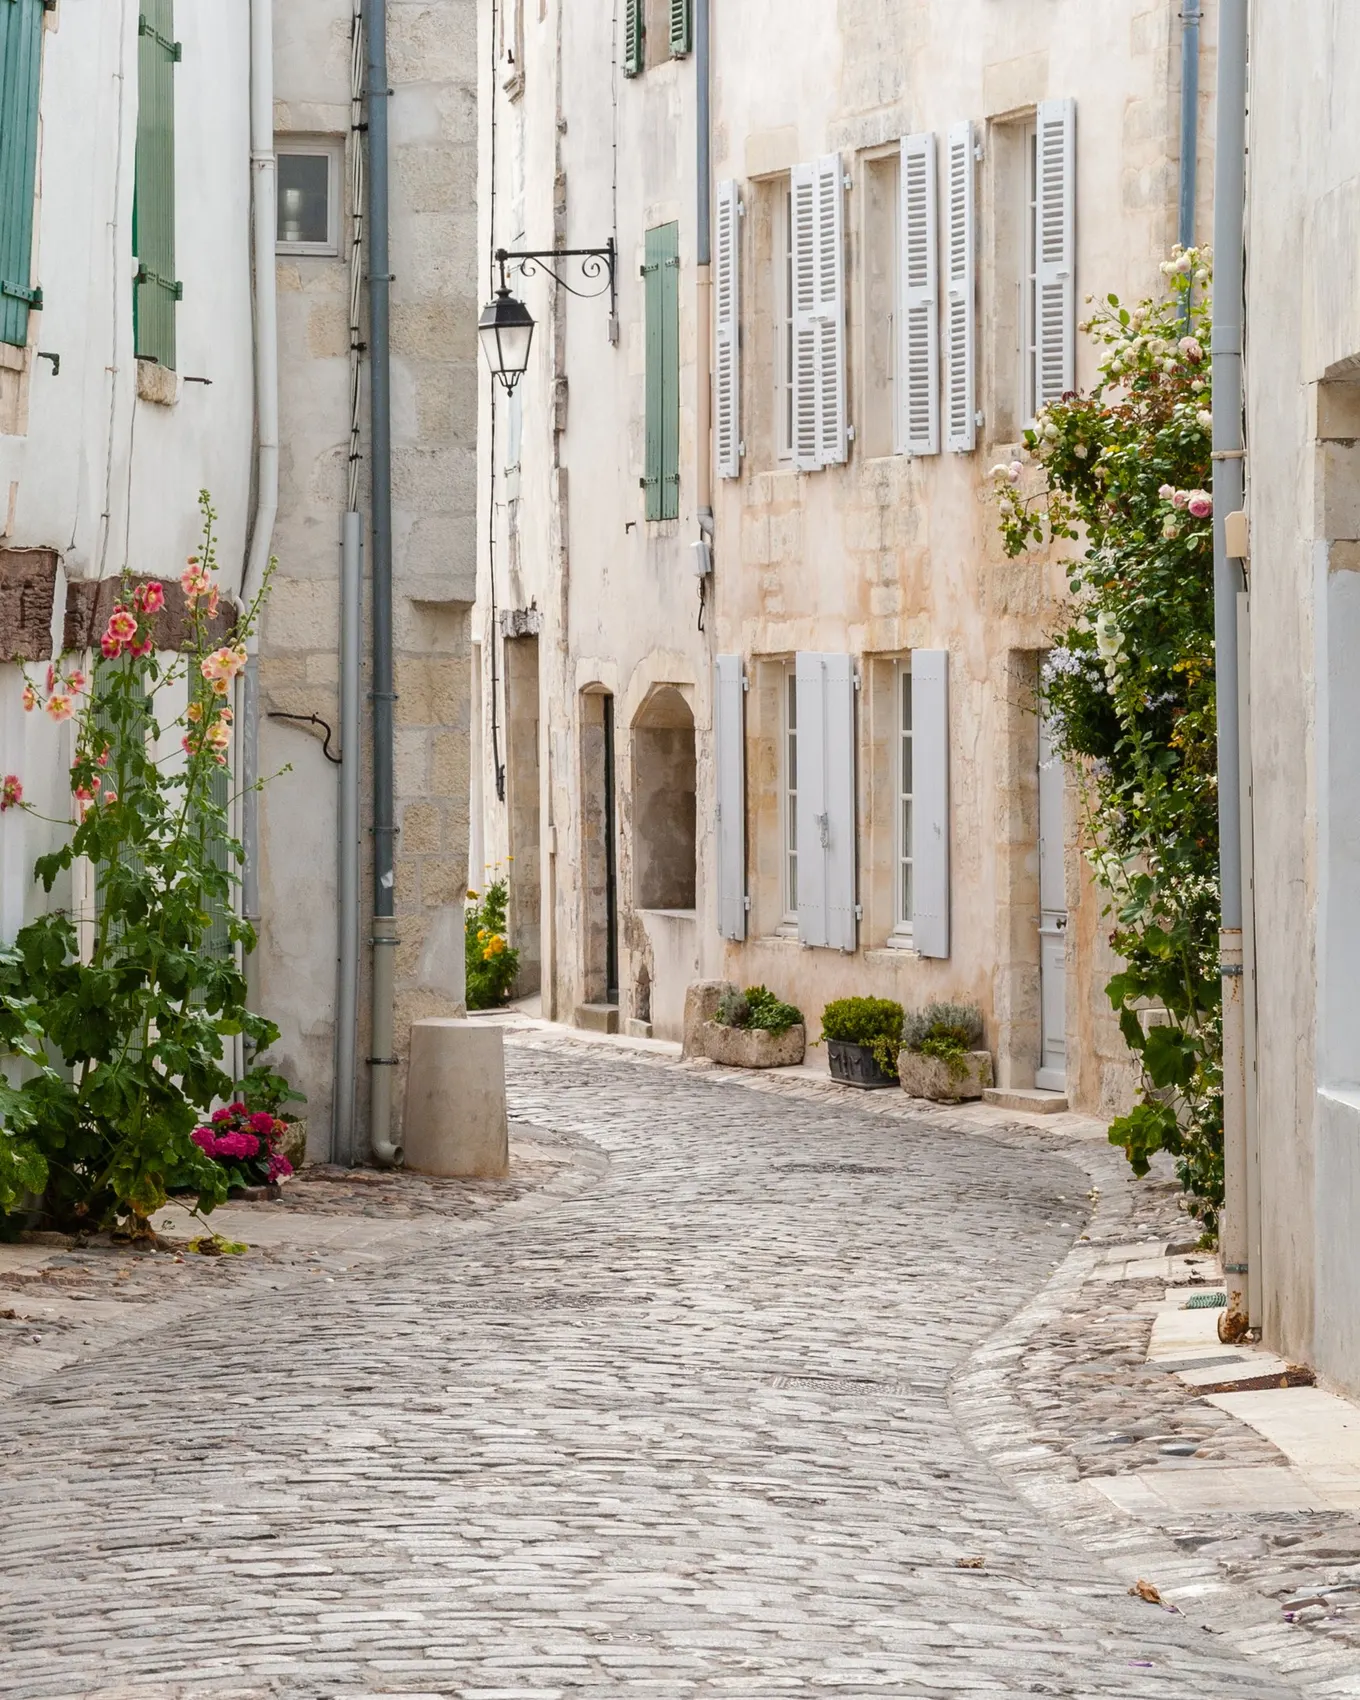
Atlantic Coast -Île de Ré -A lane with green shutters
By Jean Mascla, founder of Home SelectUpdated · 16 min read
What will you use your second home for?
A second home most often serves one of the five uses below, and each calls for a different location, property and budget. Write down your own before you look at a single listing.
The family house: repeated stays, across several generations. It needs plenty of bedrooms, outdoor space, simple upkeep and a journey that everyone accepts.
The weekend pied-à-terre: frequent, short stays; the journey matters more than the floor area, and an apartment that can be shut up quickly beats a property that needs maintaining.
The property let for part of the year: letting covers part of the running costs, if the municipality and, in a co-ownership building, its rules allow it.
The future main residence: bought with a retirement or a move in mind, it is judged on year-round life, not on August; the guide to leaving the Paris region develops this project.
The store of wealth: a rare location (a view, the seafront, a historic centre) matters most, because it is what carries value over the long term.
One property rarely serves two uses equally well: the villa designed for summer letting is not always the one you will want to open up in November. Settle on a main use and an acceptable secondary one; the brief follows from them.
Sea, mountains, countryside or city: where should you buy a second home?
The right location is the one that serves the use: the sea for long seasons, the mountains for two distinct seasons, the countryside for space, the city for a pied-à-terre you can use all year round.
Median price per m² of each municipality, DVF / DGFiP via data.gouv.fr, October 2026 release, 12 months to end of June 2026. Benchmark: a median of €9,800/m² in Paris (DVF sales register, 12 months to end of June 2026). A median describes a municipality, not an address: the view, the condition and the land make the difference.
Setting
Benchmark market
Median per m²
What drives the price
Sea, Atlantic
Villas in Biarritz
€7,900/m² (houses)
The ocean view, a beach within walking distance
Sea, Mediterranean
Houses in Bandol
€6,800/m² (houses)
A genuine sea view, access, parking
Sea, English Channel
Houses in Deauville
€6,200/m² (houses)
Proximity to the beach and the town centre
Mountains
Chalets in Chamonix
€13,800/m² (houses)
The view of the massif, winter sun
Alpine lake
Houses in Annecy
€6,100/m² (houses)
The lake view, access to the shore
Provençal countryside
Houses in Aix-en-Provence
€6,000/m² (houses)
The land, the calm, the older buildings
City
Apartments in Lyon
€4,400/m² (apartments)
The floor, outdoor space, the co-ownership building
By the sea
The sea comes at a price: in Arcachon, the median for houses reaches €8,000/m², against €3,100/m² for the Gironde as a whole (DVF / DGFiP via data.gouv.fr, October 2026 release, 12 months to end of June 2026). From Cap Ferret to the villas of Biarritz, from the île de Ré to Deauville, from Cassis to Saint-Tropez, every stretch of coast has its own market, but all raise the same questions: the Loi Littoral (coastal law), coastal risks, buildings exposed to the salt air. The guide to buying by the sea covers them.
In the mountains
Mountain markets are narrow, and some of the finest chalets sell there without ever being advertised. The median for apartments reaches €9,400/m² in Megève and €11,800/m² in Courchevel (DVF / DGFiP via data.gouv.fr, October 2026 release, 12 months to end of June 2026). A chalet in Chamonix, in a genuine valley town, can be lived in all year round, as can a house on the shore of Lake Annecy or of Lake Geneva at Évian-les-Bains. Chalet or apartment, altitude, winter access: the guide to buying in the mountains sets out the criteria.
In the countryside
The countryside sells space: a bastide around Aix-en-Provence, a mas (a Provençal farmhouse) in the Alpilles or the Luberon within reach of Avignon, a longère (a long, low farmhouse), a maison de maître (a large, stately house). Land, private drainage, a swimming pool and a garden weigh more heavily there than in town, and the SAFER (the rural land agency) holds a right of pre-emption on certain rural properties. Older houses have a set of criteria of their own, set out in the guide to buying a character property.
In the city
A city second home, in Bordeaux, Nice, Lyon or Montpellier, is often the easiest to live with: an apartment you simply lock up, cultural life in every season, a train station and an airport close by.
The south of France
Buying a holiday home in the south of France means choosing between the Côte d’Azur, Provence, the Occitanie coast and the Basque Country: a long season, but heavy summer crowds and, in exposed areas, a wildfire risk that makes brush clearance (débroussaillement) compulsory.
The journey rule: the home you actually get to
The easier a second home is to reach, the more it is lived in: a direct journey opens up weekends, an expedition confines it to the long holidays. Measure the journey door to door, not the distance on the map.
The direct route: a train or flight with no connection; every change costs you weekends.
Departure times: Friday evening, the eve of school holidays, the Sunday return; make the journey for the decisive viewing at those times.
The season: a mountain road in winter, access to an island in high summer, villages packed out during the holidays.
The last leg: whether a car is essential, parking, shops and the beach within walking distance.
Bordeaux, Lyon, Avignon, Arcachon, Biarritz, La Rochelle, Saint-Malo and Annecy can be reached by TGV high-speed train from Paris, and the Côte Fleurie by train from Gare Saint-Lazare. From abroad, you set out from the nearest international airport: Nice for the Côte d’Azur, Marseille for Provence, Bordeaux for the Bassin d’Arcachon, Geneva for the lakes and resorts of Haute-Savoie.
Take a typical case: to come every other weekend from April to October, you need a direct journey you would be happy to repeat, without fatigue, on a Friday evening; for the summer alone, a more distant address can be justified, in return for a garden or a view.
What budget should you plan for a second home?
On top of the price, allow for around 7 to 8% in acquisition costs (the so-called notary fees) on existing homes, 2 to 3% on new builds, then an annual budget that runs whether or not the property is occupied. It is this second budget, which no listing ever sets out in full, that hides the unpleasant surprises.
Cost the annual items over several years before setting your maximum price.
If you appoint a buyer’s agent: due only if the purchase completes, never before (Loi Hoguet, the French law of 1970 that regulates property professionals).
Works and equipment
Before the first season
Have them costed before committing; an in-ground swimming pool requires a standardised safety device.
Property tax (taxe foncière)
Every year
Owed by the owner on 1 January; in the year of purchase, the deed generally provides for the seller to be reimbursed pro rata.
Residence tax (taxe d’habitation)
Every year
Still levied on second homes; the municipality can increase it by 5 to 60% in a high-demand area (zone tendue).
Co-ownership service charges
Usually every quarter
The voted budget, plus calls for funds for works already decided.
Upkeep and energy
All year round
Garden, swimming pool, roof, frost-protection heating: a closed-up property needs looking after too.
Insurance
Every year
Clauses linked to the property standing empty: theft, water damage, water cut-off.
Looking after the property
Between stays
Opening and closing for the season, check visits: a relative or a concierge service.
A second home is also part of the taxable base of the real estate wealth tax (impôt sur la fortune immobilière, IFI), payable above €1.3m of net taxable real estate assets, without the 30% allowance reserved for a main residence: your wealth adviser can measure the effect.
How do you finance the purchase of a second home?
A second home is financed under the same rules as a main residence, those of the Haut Conseil de stabilité financière (the French financial stability council): a debt-to-income ratio of 35% at most, insurance included, and a term of 25 years at most. That ratio is calculated across all your loans, main residence and other properties included. In 2026, interest rates stand between 3.2 and 3.5% over twenty years.
Banks grant fewer exceptions for a second home: count on the rule, not on the exception.
The down payment most often covers at least the acquisition costs; a larger one makes approval easier.
Income from future holiday letting is counted with caution, when it is counted at all.
A cash purchase, or a mortgage agreement in principle obtained before the offer, strengthens your position: the seller gains in certainty.
At the preliminary sale agreement (compromis de vente) stage, the mortgage condition precedent, which makes the sale conditional on your loan being granted, protects the buyer: one month at least by law, often 45 to 60 days in practice. If several people buy together, a written joint-ownership agreement (convention d’indivision) settles who pays, who occupies and how to exit. A société civile (a non-trading company) can help prepare succession, but furnished letting inside it changes the tax regime: the structure should be chosen with your notaire, the public officer who draws up the deed, and your wealth adviser, before signing.
Atlantic Coast -Île de Ré -A lane with green shutters
Can you rent out your second home in France?
Yes, but renting out a second home on a short-term basis, as a furnished holiday let, has to be checked before the offer: the municipality, the co-ownership building and the property’s energy performance can restrict it, even prohibit it. The law of 19 November 2024 strengthened each of these levers.
What the law of 19 November 2024 changed
Registration: the law extends it to all furnished holiday lets, and the registration number must appear in every advertisement.
Municipalities have new tools to regulate, even limit, furnished holiday lets, including the option of lowering to 90 days a year the letting of a main residence. For a second home, it is the change-of-use authorisation, where that regime applies, that governs repeated letting to short-stay guests.
The tax treatment of this income, which is taxed as industrial and commercial profits (bénéfices industriels et commerciaux, BIC), has become less favourable, particularly for unclassified furnished lets (those with no official star rating).
A co-ownership building can now ban furnished holiday lets in units that are not main residences, by a majority of co-owners representing at least two thirds of the votes, if its rules already prohibit any commercial activity outside units designated for commercial use.
The energy performance certificate (DPE): the law subjects furnished holiday lets to energy performance requirements that tighten in stages.
Managing the lets can be entrusted to a professional whose trade it is, or done yourself. The Home Select concierge service looks after the property between your stays, billed for time spent and by quotation, with no management mandate.
Buying far from home: how do you search remotely?
A second home is often bought far from where you live: the search can be conducted remotely up to the decisive viewing, provided everything that can be checked on documents is checked before you travel. The deed can also be signed remotely, by a notarial power of attorney taken by video conference; funds are transferred only to the notaire, after the notaire’s bank details have been checked by telephone. The guide to buying remotely details each step.
What can be checked on documents
The risk report (état des risques), handed over from the first viewing since 1 January 2023: flooding, coastal submersion, wildfire, coastline retreat, depending on the municipality.
The mandatory diagnostic reports: DPE, asbestos and lead depending on the age of the building, electricity and gas depending on that of the installations, termites depending on the zone and, where there is no mains drainage, an inspection of the private drainage system less than three years old.
The co-ownership building: its rules, meeting minutes, maintenance log, service charges, clauses on letting.
Planning: the local urban plan (plan local d’urbanisme), servitudes (legal easements and restrictions) and, in the surroundings of a historic monument (a defined perimeter or, failing that, 500 metres within its line of sight) or in a remarkable heritage site (site patrimonial remarquable), the consent of the architecte des Bâtiments de France (the State heritage architect) to exterior works.
The price, set against actual sales on the street and in the neighbourhood.
What only the season shows
A video conveys neither the damp of a house closed up all winter, nor the bustling bar beneath the windows in July. So choose an area you know in both seasons, the chalet road under snow included, and get these questions answered before you travel: the decisive viewing, grouped into a single trip, is there to confirm, not to discover.
What happens when you resell a second home?
Capital gains tax is due on the gain made when a second home is resold, with allowances that increase with the length of ownership; the sale of a main residence is exempt from it. The notaire calculates the tax and deducts it from the sale price; the capital gains tax simulator estimates it in advance from your prices.
Income tax and social charges (prélèvements sociaux) each have their own allowance schedule, up to full exemption after a long period of ownership, and a surtax applies to the highest gains. A second home that has become a main residence, genuinely occupied on the day of the sale, is exempt: the authorities check that it was really lived in.
Resale is prepared from the day you buy, by looking at the depth of the market: over the 12 months to end of June 2026, 8,045 sales were recorded in Nice, 784 in Biarritz and 190 in Saint-Tropez (DVF / DGFiP via data.gouv.fr, October 2026 release, 12 months to end of June 2026). On a narrow market, a rare property sells well but sometimes slowly; a location that nobody can reproduce remains the best protection for resale.
How Home Select searches for your second home
Home Select, a buyer’s agent on the buyer’s side, conducts the search for a second home remotely, video viewings included, up to the decisive viewing: you travel only for the shortlisted properties, in a single trip. Home Select runs the search under the direction of its management and draws on a network of 15,000 professional partners.
The brief, written up after a first conversation by video call or phone: use, seasons, journey, full budget.
The hunt across the whole market: Home Select monitors 1,700 listing sites, receives at least 100 off-market properties every day from its network and makes its first proposals within 48 hours of the mandate being signed.
The pre-viewing by commented video and an analysis sheet for every shortlisted property, with the price benchmarked against DVF sales, address by address.
The decisive viewings, grouped together: Home Select brings them down to 3 on average, or about 15 hours of your time, against 40 viewings or more and about 150 hours for a buyer on their own.
The offer and the negotiation, where Home Select obtains 6% off the asking price on average, then securing the preliminary sale agreement: review, diagnostics, co-ownership building.
Coordination of the notaire, the mortgage broker and the diagnostic surveyors up to the deed, and afterwards: tradespeople, administrative formalities, settling in.
Home Select charges 2.5% of the net purchase price on the Exclusive offer (an exclusive mandate), minimum €10,000 incl. VAT; the Confidential offer, on a simple mandate and reserved for projects of €2m and above, brings the same full service at 1.5%, with off-market properties only. On top of the fees, Home Select receives 10% of the negotiated reduction: it is also paid on what you save. Nothing is due before the authentic deed, and the mandate, of twelve months at most, can be terminated at any time on seven days’ notice. The detail is on the pages for the fees, the method and the buyer’s agent for a second home.
Since 2011, Home Select has guided more than 1,200 buyers, with an average search time of 45 days to an accepted offer and a 4.8/5 rating on Google (145 reviews). Every market presented on the site has its own page, DVF prices and neighbourhoods included: for example, buyer’s agent in Arcachon, buyer’s agent in Megève or buyer’s agent in Saint-Tropez.
Frequently asked questions
Where should you buy a second home in France?
A holiday home in France is bought where it will serve your use and be easy to reach. The sea, from the Bassin d’Arcachon to the Côte d’Azur, suits the long seasons; the mountains, from Megève to Lake Annecy, offer two seasons; Provence gives you space; Bordeaux or Lyon, a city pied-à-terre. Then compare prices municipality by municipality.
How do you buy a holiday home in the south of France?
To buy a holiday home in the south of France, fix the use and the season, then choose between the Côte d’Azur, Provence, the Occitanie coast and the Basque Country according to your journey. Check three points that weigh particularly heavily there: the wildfire risk and the brush-clearance obligations, the local rules on holiday letting, and summer crowds. Visit out of season and set the price against actual sales.
What costs and taxes should you allow for on top of the price of a second home in France?
On purchase, around 7 to 8% in acquisition costs on existing homes, 2 to 3% on new builds. Every year after that: the property tax (taxe foncière), the residence tax on second homes (taxe d’habitation), which can be increased by 5 to 60% in a high-demand area (zone tendue), co-ownership service charges, upkeep, insurance and looking after the property between stays, whether or not the home is occupied.
Can you get a mortgage for a second home?
Yes, under the same standards as for a main residence: a debt-to-income ratio of 35% at most, insurance included, calculated across all your loans, and a term of 25 years at most. In 2026, rates stand between 3.2 and 3.5% over twenty years. Banks do, however, grant fewer exceptions for a second home, and look closely at the down payment.
Can you rent out a second home as a furnished holiday let?
Yes, you can rent out a second home in France as a furnished holiday let if the municipality and the co-ownership rules allow it. The law of 19 November 2024 extends registration to all furnished holiday lets, strengthens municipalities’ powers, makes their taxation less favourable and subjects them to energy performance requirements. Have the local rules checked before the offer, including any change-of-use authorisation, the co-ownership building and the DPE (energy performance certificate).
Do you have to pay the taxe d’habitation (residence tax) on a second home?
Yes: the taxe d’habitation was abolished for main residences, not for second homes. It is owed by the person who has the property at their disposal on 1 January, and municipalities in a high-demand area (zone tendue) can increase it by 5 to 60%. Ask the seller for the latest notice before you buy.
Is capital gains tax payable when you sell a second home?
Yes: the gain on a second home is subject to income tax, to social charges and, for the highest gains, to a surtax, with allowances that increase with the length of ownership; full exemption comes only after a long period of ownership. The sale of a main residence, by contrast, is exempt. The notaire (the public officer who draws up the deed) calculates the tax and deducts it from the sale price.
How much does a buyer’s agent cost for a second home?
Home Select charges 2.5% of the net purchase price on the Exclusive offer, minimum €10,000 incl. VAT. The Confidential offer, reserved for projects of €2m and above, costs 1.5% for the same full service, on a simple mandate and on off-market properties only. On top of the fees, Home Select receives 10% of the negotiated reduction: it is also paid on what you save. Both are 100% on success: no advance, no file fee, with fees paid at the signing of the authentic deed.
Your request is already sent, simply pick what suits you.
A buyer’s agent calls you back within one working day.
🇫🇷+33
An error occurred. Please try again.
Then answer 3 quick questions to be matched with the right buyer's agent.
Home Select processes your data (name, email, phone, project) to handle your request and contact you. It is recorded in our follow-up tool and read by the buyer's agent in charge of your project. Our technical providers access it for hosting, email and checking that your email and number are real, some of them from the United States under the safeguards set by the GDPR. We keep it for three years after our last exchange, or five years after the end of our assignment if you entrust it to us, as French anti-money-laundering law requires. To access, correct or erase it, or to object to its use: contact@home-select.fr. Details in our privacy policy.
Your hunter calls you back within one working day.
Resume your request?
You started a request recently. Pick up where you left off, or start over.
Your answers are kept for 24 hours.
What is your project?
Takes 1 minute, no commitment.
Where are you looking?
Select one or more cities or areas
Your budget?
€
You pay only when Home Select finds it.
Anything to add?
Optional. Add any useful details: specifics about your search, constraints or your availability.
This helps your buyer's agent prepare for your call.
An expert will contact you shortly
Your brief
Confidential search: your file goes to a senior buyer's agent.
60 rue François 1er, 75008 Paris · FCI member
FeesOne month’s rent excluding charges, plus VAT, with a minimum of €2,000 including VAT. Payable only when the lease is signed. No application fee.
Step 1 of 2 · Your search
What are you looking for?
Furnished, unfurnished or both?
In which city?
One or more cities or areas.
€ / month
Charges included, as in the listings.
You would like to move in
Two minutes, no documents needed at this stage.
FeesOne month’s rent excluding charges, plus VAT, with a minimum of €2,000 including VAT. Payable only when the lease is signed. No application fee.
Step 2 of 2 · Your situation
Your situation
These answers let Home Select tell you quickly, and frankly, whether your search can succeed on the market in your city.
You are applying
€ / month
Before tax, regular bonuses included, for everyone applying.
Main applicant’s employment
Your company is based in France
Number of annual accounts filed
To strengthen your file
Optional for your profile. A guarantee reassures landlords.
Guarantor’s situation
€ / month
Who it is for, why you are moving, what matters to you. Do not include sensitive information (health, origin, religion, family situation).
Your contact details
🇫🇷+33
Reply within 24 business hours.
Home Select processes your data (name, email, phone, project, employment, income, guarantee) to review your rental request and contact you. Your answers are compared with the criteria landlords apply, then read by Home Select’s rental specialist. A request that cannot succeed receives a written reply within 24 business hours, and you can ask for it to be reviewed again at contact@home-select.fr. Our technical providers access it for hosting, email and checking that your email and number are real, some of them from the United States under the safeguards set by the GDPR. A request that does not lead to an assignment is erased after three months; otherwise, we keep your data for three years after our last exchange, or five years after the end of our assignment if you entrust it to us, as French anti-money-laundering law requires. To access, correct or erase it, or to object to its use: contact@home-select.fr. Details in our privacy policy.
FeesOne month’s rent excluding charges, plus VAT, with a minimum of €2,000 including VAT. Payable only when the lease is signed. No application fee.
Your file
Your file matches what landlords expect
Book your meeting with Stéphane Martins, rental specialist. He confirms it after reading your file, within 24 business hours.
Choose your time slot
Times shown in Paris time.
Confirmation arrives by email and text message.
FeesOne month’s rent excluding charges, plus VAT, with a minimum of €2,000 including VAT. Payable only when the lease is signed. No application fee.
Your request
Your request is in good hands
Stéphane Martins, rental specialist, is reviewing your file and will reply within 24 business hours.
Home Select processes your data (name, email, phone, project) to handle your request and contact you. It is recorded in our follow-up tool and read by the buyer's agent in charge of your project. Our technical providers access it for hosting, email and checking that your email and number are real, some of them from the United States under the safeguards set by the GDPR. We keep it for three years after our last exchange, or five years after the end of our assignment if you entrust it to us, as French anti-money-laundering law requires. To access, correct or erase it, or to object to its use: contact@home-select.fr. Details in our privacy policy.
Home Select processes your data (name, email, phone, project, employment, income, guarantee) to review your rental request and contact you. Your answers are compared with the criteria landlords apply, then read by Home Select’s rental specialist. A request that cannot succeed receives a written reply within 24 business hours, and you can ask for it to be reviewed again at contact@home-select.fr. Our technical providers access it for hosting, email and checking that your email and number are real, some of them from the United States under the safeguards set by the GDPR. A request that does not lead to an assignment is erased after three months; otherwise, we keep your data for three years after our last exchange, or five years after the end of our assignment if you entrust it to us, as French anti-money-laundering law requires. To access, correct or erase it, or to object to its use: contact@home-select.fr. Details in our privacy policy.
You arrived through one of Home Select’s ads or campaigns.Ad measurement.Do you agree to Home Select measuring how well it works? Home Select will know which campaign brought you here and, if you get in touch, the ad platform will only learn that its ad worked, without receiving your contact details.Do you agree to Home Select measuring how well its ads work? If you arrive through one of them, Home Select will know which one and, if you get in touch, the ad platform will only learn that its ad worked, without receiving your contact details.Learn moreYour current choice: .